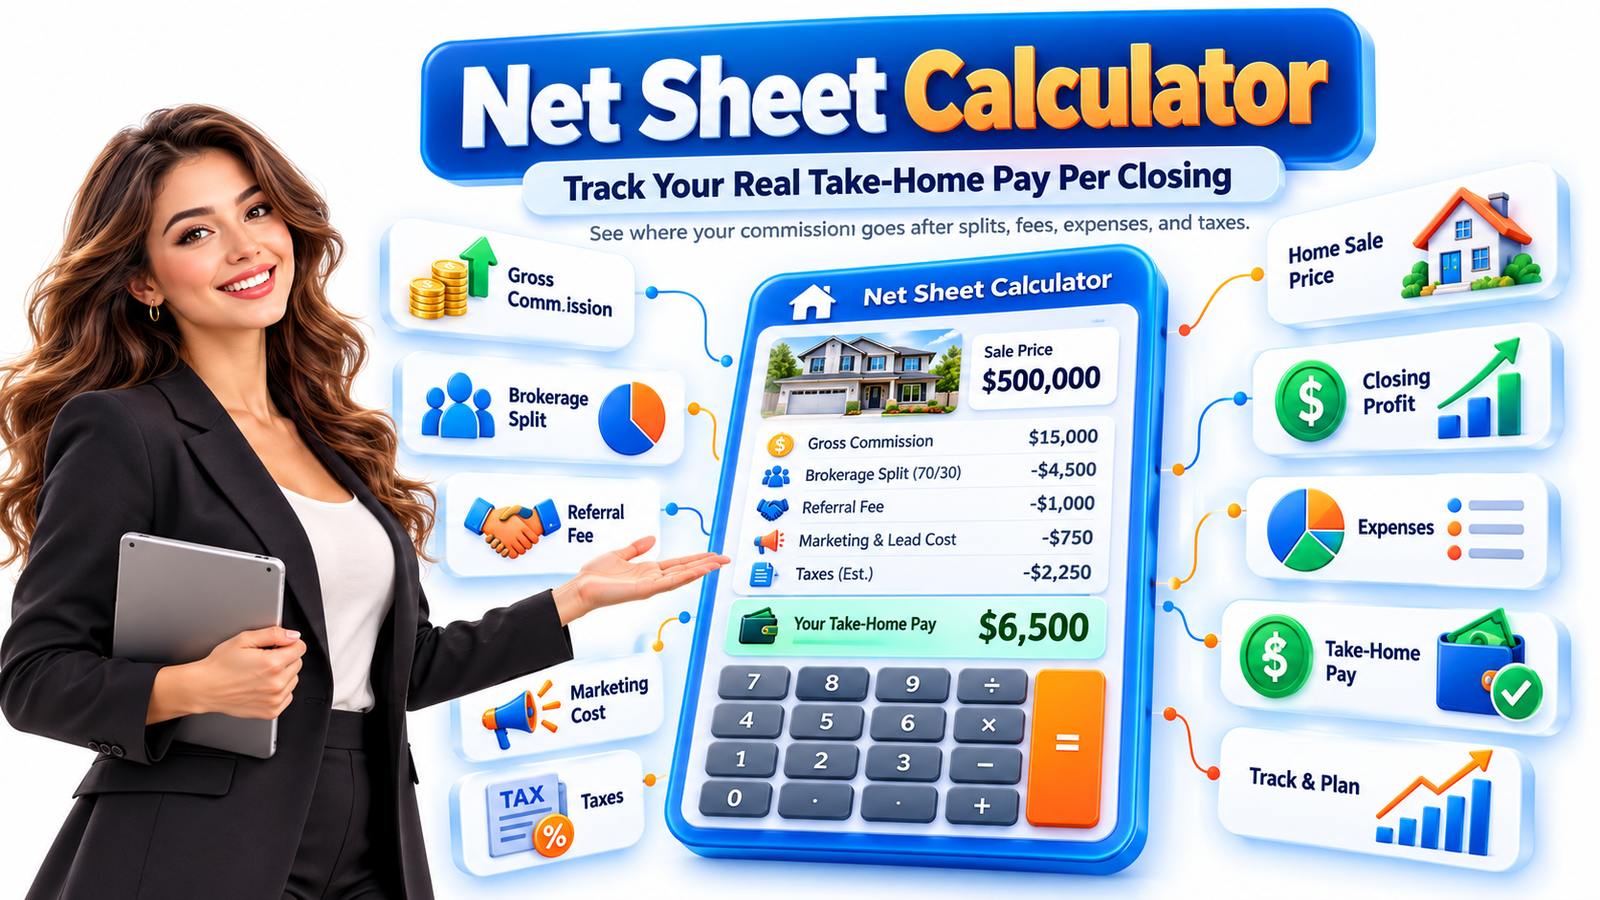
How to Track Your Real Take-Home Pay per Closing
A real estate agent closes the year with $140,000 in gross commission income.
On paper, that sounds like success.
The social-media version of the story might include a screenshot of the production number, a celebratory dinner, a “six-figure agent” caption and a plan to double volume next year.
But there is a number that matters far more than GCI.
How much of that money did the agent actually keep?
After brokerage splits, referral fees, transaction fees, lead-generation costs, listing expenses, software subscriptions, mileage, assistants, marketing, professional dues and taxes, the difference between gross commission income and real take-home income can be enormous.
That is why financial literacy for Realtors and real estate agents is not simply about knowing how much commission was earned. It is about understanding the economics of every closing.
A practical real estate net sheet calculator can help turn commission checks into useful business intelligence.
Instead of asking only:
“How much was my commission?”
A financially disciplined agent asks:
“What did this transaction actually produce after expenses?”
That one change in thinking can reshape pricing decisions, lead-generation strategy, marketing budgets, team structure and long-term profitability.
GCI Is Important, but It Is Not Your Salary
Gross commission income, commonly called GCI, is one of the most frequently discussed numbers in real estate.
It is useful.
But it can also be misleading when treated as personal income.
If a transaction generates a $12,000 gross commission, that does not necessarily mean $12,000 becomes spendable income.
The commission may pass through several layers before becoming true take-home pay.
Depending on the agent’s business structure and brokerage arrangement, deductions may include a brokerage split, franchise or royalty fee, transaction fee, referral fee, team split, lead-source cost, marketing expense, staging contribution, photography, signs, travel, software, administrative support and tax reserves.
The number deposited into a business account may still not be personal profit.
That distinction is where many agents lose visibility.
A healthy real estate business should therefore track at least three separate numbers:
Gross commission income → transaction-level net income → business or personal take-home income.
Confusing those numbers can make an agent appear more profitable than the business really is.
Why a $100,000 GCI Agent May Not Have a $100,000 Income
Consider an agent who produces $120,000 in annual GCI.
That figure sounds impressive, but suppose the business also has $24,000 in brokerage and transaction-related costs, $18,000 in lead-generation expenses, $9,000 in software and marketing costs and $7,000 in additional operating expenses.
The business is already down to approximately $62,000 before considering applicable income taxes, self-employment taxes, payroll obligations, retirement contributions or other personal and business liabilities.
The exact treatment will vary significantly according to location, entity structure and individual circumstances, but the principle remains the same:
Revenue and income are not the same thing.
This is why agents who understand real estate profit margins often make better decisions than agents who focus only on transaction count.
One agent might close 40 transactions and struggle financially.
Another might close 24 transactions and operate an extremely profitable business.
The difference is often not selling ability.
It is financial visibility.
What Is a Real Estate Agent Net Sheet Calculator?
A real estate agent net sheet calculator is a financial tracking tool that estimates how much money remains from a commission after transaction-specific expenses and deductions are accounted for.
It is different from the seller net sheet often used during listing presentations.
A seller net sheet estimates what the property owner may receive after mortgage payoff, closing costs, taxes, commissions and other expenses.
An agent commission net sheet focuses on the agent’s side of the transaction.
It answers questions such as:
How much commission did the transaction generate?
What portion went to the brokerage?
Was there a referral fee?
How much did the lead cost?
What did photography, staging, marketing or administrative support cost?
What percentage should be reserved for estimated taxes?
What was the approximate take-home amount?
What percentage of GCI became operating profit?
When an agent tracks these numbers consistently, the calculator becomes more than an accounting worksheet.
It becomes a decision-making system.
The Simple Formula Every Agent Should Understand
At its most basic level, the calculation looks like this:
Gross Commission Income − Transaction Costs − Allocated Business Expenses = Estimated Net Transaction Income
For example, imagine a transaction produces $10,000 in GCI.
The brokerage split and transaction costs total $2,500.
A referral partner receives $1,500.
Marketing and transaction expenses total $600.
The lead source cost allocated to that transaction is $700.
That leaves approximately:
$10,000 − $2,500 − $1,500 − $600 − $700 = $4,700
The agent generated $10,000 in GCI.
But the approximate transaction contribution before taxes and certain overhead expenses is only $4,700.
That is a completely different financial picture.
And once you see the business this way, decisions become easier.
The Numbers Your Commission Net Sheet Should Track
A useful calculator should begin with the property and transaction details, but its most important job is to capture every cost that reduces profitability.
At minimum, an agent should be able to record the sale price, commission rate or commission amount, brokerage split, cap status where applicable, transaction fee, franchise or royalty fee, referral fee, team split, lead cost, marketing expense, photography or video costs, staging-related expenses, gifts, mileage or travel allocations, administrative charges and other closing-specific expenses.
The calculator may also include an estimated tax reserve.
However, tax calculations should be treated as planning estimates rather than tax advice because obligations vary significantly according to jurisdiction, entity structure, deductions and individual circumstances.
The most useful final output is not just a dollar amount.
It should also show the net-to-GCI percentage.
For example:
GCI: $8,000
Estimated transaction net: $4,800
Net-to-GCI ratio: 60%
That percentage makes different transactions easier to compare.
Your Net-to-GCI Percentage May Be More Useful Than Your Sales Volume
Many real estate agents track volume obsessively.
“$8 million sold.”
“$12 million sold.”
“$20 million production.”
Those figures can demonstrate market activity, but they do not necessarily reveal business performance.
Imagine two agents.
Agent A closes $15 million in sales and generates $300,000 GCI but spends aggressively on purchased leads, advertising and team costs.
Agent B closes $9 million and generates $210,000 GCI but operates with a strong referral network, lower acquisition costs and leaner overhead.
If Agent A retains 38% after major business expenses while Agent B retains 64%, Agent B may operate the healthier business despite producing less sales volume.
This is why real estate financial literacy requires a shift from vanity metrics to profitability metrics.
Production can build reputation.
Profitability builds durability.
Your Most Expensive Closing May Be Hiding in Plain Sight
One of the most useful insights from a real estate commission calculator is that two transactions with identical commission income can have dramatically different economics.
Suppose Transaction A and Transaction B each generate $9,000 in GCI.
Transaction A comes from a past-client referral. Marketing expense is minimal and there is no referral fee.
Transaction B comes from a paid lead source, requires several months of follow-up, includes a 25% referral fee and needs additional marketing support.
The top-line commission is identical.
The profitability is not.
Without transaction-level tracking, both deals appear equally valuable.
With a proper net sheet, an agent can see which client-acquisition channels consistently produce higher take-home income.
That insight can influence where the next marketing dollar should go.
The Hidden Cost of Purchased Leads
Lead-generation services can create opportunities, but the cost of those opportunities should be measured against actual closings.
Suppose you spend $2,000 per month on a lead platform.
During the year, the platform costs $24,000.
It generates eight closed transactions.
Your effective acquisition cost is roughly $3,000 per closing before considering staff time, CRM expenses and follow-up effort.
If the average transaction produces $7,500 in GCI, that acquisition cost represents 40% of the gross commission before brokerage expenses and other costs.
That does not automatically make the lead source bad.
It means you need the numbers.
An agent net sheet calculator helps you evaluate marketing based on net revenue, not simply the number of leads generated.
Measure Cost per Closing, Not Just Cost per Lead
Marketers frequently discuss cost per lead.
Agents should also track cost per closed transaction.
Suppose Marketing Channel A generates leads for $18 each while Marketing Channel B generates leads for $60 each.
At first glance, Channel A appears better.
But if Channel A needs 250 leads to produce one closing while Channel B needs only 45, the economics change dramatically.
Real business decisions should follow the entire funnel:
Marketing spend → leads → appointments → signed clients → closed transactions → GCI → net income.
The last number matters most.
Calculate Your Real Hourly Value
There is another number many agents rarely calculate:
profit per hour worked.
A transaction that produces $5,000 in net contribution after 25 hours of work is financially different from a transaction producing the same amount after 70 hours of work.
You do not need to record every minute.
Even rough estimates can reveal patterns.
One client source may create smooth transactions with prepared clients and predictable timelines.
Another may create repeated showings, poor qualification, extended follow-up and low conversion rates.
When agents understand their approximate time investment, they can improve systems and identify where automation, delegation or better qualification may be needed.
Why Six-Figure GCI Can Create a False Sense of Security
Real estate income is irregular.
A strong month can make an agent feel financially comfortable even when annual profitability is weak.
This is especially dangerous during high-volume periods.
Several commissions arrive close together.
The business account looks healthy.
Advertising increases.
Subscriptions accumulate.
Lifestyle spending rises.
Then transactions slow.
Taxes become due.
Renewals appear.
Quarterly expenses arrive.
Suddenly the six-figure producer feels cash-poor.
The solution is not necessarily selling more homes.
Sometimes the solution is understanding the money already moving through the business.
Separate Business Revenue From Personal Income
One of the most useful habits for agents is mentally separating incoming commission from personal spending money.
A commission deposit is business revenue first.
Depending on your business setup, portions may need to cover brokerage obligations, tax reserves, operating expenses, payroll, future marketing, insurance, savings or other business requirements.
Only after these obligations are accounted for does the remaining amount represent potential owner compensation.
A structured commission net sheet makes that process visible immediately after closing.
Instead of seeing a $15,000 commission and thinking, “I earned $15,000,” the agent sees the transaction in layers.
That creates more disciplined financial behavior.
Build a Tax Reserve Into Your Workflow
Taxes can be one of the largest outflows for self-employed real estate professionals.
The appropriate amount to reserve depends on many factors, including income level, country, state or province, business entity, deductions and other financial circumstances.
For that reason, there is no universal tax percentage that every agent should follow.
However, agents can still build a tax reserve field into their calculator.
The percentage should come from guidance provided by a qualified tax professional familiar with the agent’s circumstances.
Once established, the calculator can estimate how much money from each closing should remain untouched for future obligations.
That can prevent a common problem:
Spending gross commission and treating taxes as a future emergency.
Watch Your Brokerage Split in Real Numbers
Percentage splits can feel abstract until converted into annual dollars.
An agent may think:
“I have a 70/30 split.”
But if the agent generates $180,000 GCI before reaching a cap or threshold, the total economic impact can be significant depending on the brokerage agreement.
There may also be administrative fees, franchise charges, transaction fees, desk fees, technology charges or other costs.
This does not mean the brokerage is overpriced.
A brokerage may provide exceptional coaching, leads, compliance support, brand recognition, technology, training or transaction management.
The correct question is:
What value am I receiving for the total cost?
A net sheet makes the cost visible so that value can be evaluated rationally.
Track Referral Fees Separately
Referral fees deserve their own category.
A 25% referral on a $12,000 commission equals $3,000.
If you receive multiple referral-generated transactions every year, referral relationships may still be highly profitable because the acquisition cost can be predictable and the lead may arrive with stronger intent.
The mistake is not paying the referral fee.
The mistake is ignoring it when calculating profitability.
Track referral-generated transactions as their own client-acquisition category.
Over time you can compare:
past clients, personal referrals, portal leads, paid advertising, social media, organic search, open houses, geographic farming, agent referrals and other sources.
You may discover that the “free” marketing channel is not actually your most profitable one—or that an expensive-looking source produces excellent lifetime value.
One Closing Is Not the Entire Customer Value
Transaction-level profitability matters, but it should not encourage short-term thinking.
A client may close today, refer two people next year and sell another property five years later.
That means the economic value of the relationship can exceed the first transaction.
This is why serious agents should eventually track both transaction profitability and client lifetime value.
A client who generates $4,000 in net income on the first transaction but later produces $20,000 through repeat business and referrals could be much more valuable than a one-time client who initially produced a higher commission.
Financial literacy should improve relationships, not reduce people to spreadsheet cells.
The purpose is to understand where sustainable business comes from.
Use the Calculator Before Accepting Expensive Lead Programs
One of the strongest uses of historical net sheet data is forecasting.
Imagine a lead company offers an agent a program costing $1,500 monthly.
Instead of evaluating the offer based on testimonials, the agent can use existing data.
If your historical average GCI is $8,500 per transaction, average post-split commission is $6,000 and average transaction-related expense is $500, you already understand approximately how much financial contribution a typical closing creates.
Now you can estimate how many additional transactions the program must generate before it becomes economically worthwhile.
This turns marketing from a guessing game into a business decision.
A Better Way to Evaluate Your Next Closing
After every transaction, ask four questions.
What was the gross commission?
What did the transaction cost me?
What remained?
Where did the client come from?
Those four answers begin building a powerful business intelligence database.
After 25, 50 or 100 transactions, patterns become visible.
You may discover that certain price ranges produce better margins.
You may see that repeat clients close faster.
You may realize that one advertising channel consumes far more money than expected.
You might discover that a service you considered expensive actually saves enough time to justify its cost.
The calculator does not make those decisions for you.
It gives you the evidence needed to make them intelligently.
The Real Estate Profitability Dashboard Worth Building
As your tracking system becomes more mature, your dashboard can monitor annual GCI, estimated net business income, average GCI per closing, average transaction net, operating expense percentage, brokerage cost percentage, lead-generation cost, cost per closing, net-to-GCI percentage and profit by lead source.
You can also compare performance by month, quarter, price range, neighborhood or transaction type.
The goal is not to create a complicated accounting system.
The goal is to make the most important financial numbers visible enough that you actually use them.
Your accountant or bookkeeping platform may handle official financial records.
Your transaction profitability dashboard helps you manage the business.
Those are related functions, but they are not identical.
Example: What a $15,000 Commission Could Really Look Like
Consider a hypothetical closing generating $15,000 in GCI.
Brokerage-related costs: $3,000
Referral fee: $2,000
Lead acquisition allocation: $1,250
Photography, marketing and transaction expenses: $750
Remaining before other overhead and taxes: approximately $8,000
The agent did not “lose” $7,000.
Some of those expenses may have been necessary to produce and support the transaction.
The useful information is that the business retained approximately $8,000 before additional obligations.
Now imagine repeating the calculation across 30 transactions.
That data could change how the agent negotiates services, evaluates advertising, budgets marketing and chooses lead sources.
The Number to Calculate at the End of Every Month
At the end of each month, calculate your overall net retention rate.
A simplified version is:
Estimated net business income ÷ GCI × 100
If an agent generates $20,000 GCI and approximately $12,000 remains after selected business costs, the retention rate is 60%.
Track the same metric consistently.
One month by itself may not mean much.
Twelve months creates a trend.
If GCI rises 25% but net income rises only 4%, the business may be experiencing expense creep.
That deserves attention.
Expense Creep Can Quietly Consume Growth
Expense creep happens when business costs grow gradually without producing proportional results.
One new CRM.
Another lead service.
An upgraded website.
A premium design tool.
A virtual assistant.
Video software.
A transaction platform.
Several automation products.
None may appear expensive individually.
Together, they can absorb thousands of dollars annually.
The right question is not:
“Do I use this software?”
The stronger question is:
“Does this expense help generate revenue, save meaningful time, reduce risk or improve client service enough to justify its cost?”
If not, it may be time to reconsider it.
Do Not Confuse Cost Cutting With Profitability
Tracking expenses does not mean choosing the cheapest option.
Cheap photography that weakens a listing presentation may be a poor decision.
Removing a skilled transaction coordinator may create more administrative work than the savings justify.
Dropping an effective CRM could damage follow-up.
The objective is not minimum spending.
The objective is productive spending.
Strong financial management means knowing which expenses create leverage and which simply create recurring bills.
Turn the Net Sheet Into a Commission Planning Tool
Your net sheet becomes especially powerful when used before a transaction rather than only afterward.
You can model different scenarios.
What happens if there is a referral fee?
What happens if your brokerage cap has already been reached?
What happens if the listing requires premium marketing?
What happens if a team split applies?
What happens if the transaction requires several thousand dollars of acquisition expense?
Scenario planning helps you understand your potential economic outcome before the closing arrives.
It can also prevent emotionally confusing gross income with actual financial gain.
New Agents Need This Habit From Their First Closing
Early-career agents may think profitability analysis is something to worry about after reaching six figures.
The opposite is true.
Financial habits are easier to establish before the business becomes complicated.
Track every closing from the beginning.
Record where each client came from.
Track direct transaction expenses.
Review your recurring overhead.
Separate revenue from take-home income.
Create a tax-reserve strategy with professional guidance.
These practices may seem small during the first few transactions.
After several years, the data becomes extremely valuable.
Experienced Agents Need It Even More
Established agents often have more complex businesses.
Team members, assistants, advertising agreements, listing marketing, referral networks, coaching programs, software tools and administrative services can make real profitability difficult to see.
High production can hide inefficiency.
An agent generating $500,000 GCI may assume the business is performing exceptionally well.
But if operating costs have increased at the same pace—or faster—the business may be producing less profit for every dollar earned.
Growth without financial clarity can create a larger but weaker business.
From Commission Chaser to Business Owner
There is a major psychological difference between asking:
“How many more homes can I sell?”
and asking:
“How can I build a more profitable, resilient real estate business?”
The first question focuses on volume.
The second focuses on economics.
Neither is inherently wrong.
But experienced business owners understand that revenue growth works best when accompanied by margin awareness.
A strong year is not simply a year with higher GCI.
It is a year where revenue, profitability, cash reserves, client satisfaction and business sustainability improve together.
Your Commission Check Should Tell You a Story
Every closing contains information.
The lead source tells you where demand came from.
The conversion journey tells you how difficult the client was to acquire.
The transaction expenses tell you what it cost to serve them.
The commission tells you the revenue generated.
The net sheet tells you what the transaction actually contributed to your business.
When that information is stored consistently, your financial history becomes a strategic asset.
You stop guessing about which marketing channels work.
You stop assuming higher price points automatically mean better transactions.
You stop judging your business by impressive top-line numbers.
You begin making decisions from evidence.
Use a Simple Rule: Every Closing Gets a Net Sheet
The easiest financial system is one you will actually maintain.
Make the process part of your closing workflow.
When the transaction closes, update the commission amount, brokerage deductions, referral fees, transaction expenses, lead-source costs and estimated tax reserve.
Then record the approximate transaction net.
The process may require only a few minutes.
Those few minutes can provide years of useful business data.
Your Real Goal Is Not Bigger GCI
There is nothing wrong with celebrating GCI milestones.
$100,000.
$250,000.
$500,000.
$1 million.
They represent real effort and production.
But they are incomplete measurements of financial success.
The number capable of changing your business is what remains after the cost of generating that revenue is understood.
A smaller business with strong margins, healthy cash reserves, predictable lead generation and loyal repeat clients can be far more valuable than a high-volume business held together by rising expenses.
So the next time a commission check arrives, do not stop at the gross number.
Run the transaction through your net sheet.
Measure the cost.
Calculate the estimated retained income.
Record the lead source.
Compare the margin.
Then use that information to make the next transaction more profitable.
Want to understand whether your real estate business is truly growing? Start tracking your net income per closing, not just your GCI. A simple commission net sheet can turn every completed transaction into data you can use to improve pricing, marketing, lead generation and long-term profitability.
And if you already track your numbers, make the next step deeper: review your rolling 90-day and 12-month averages. That gives returning readers and established agents a reason to revisit their financial dashboard regularly rather than treating profitability as a once-a-year accounting exercise.
Frequently Asked Questions
1. What is a real estate agent net sheet calculator?
A real estate agent net sheet calculator estimates how much commission income remains after applicable transaction costs such as brokerage splits, referral fees, lead expenses, marketing costs and other selected business expenses. It helps agents compare gross commission income with estimated transaction-level profitability.
2. How do Realtors calculate take-home pay from a commission?
Start with the gross commission generated by the transaction. Subtract brokerage-related deductions, team or referral fees, direct transaction expenses, lead-generation costs and other relevant allocations. After that, account separately for estimated tax obligations and business overhead based on guidance appropriate to your circumstances. The resulting figure provides a more useful estimate of take-home economics than GCI alone.
3. What percentage of GCI should a real estate agent keep?
There is no universal percentage that applies to every agent. Retention rates vary according to brokerage arrangements, team structure, lead costs, advertising strategy, market, taxes, business model and operating expenses. The more useful approach is to track your own net-to-GCI percentage consistently and look for trends over time.
4. Why should Realtors track profit by lead source?
Different lead sources can produce very different acquisition costs, conversion rates, referral fees and client lifetime values. Tracking profit by source helps agents understand which marketing channels produce the strongest financial return rather than judging channels only by lead quantity.
5. Is a commission net sheet the same as bookkeeping or tax accounting?
No. A commission net sheet is primarily a planning and business-management tool. Formal bookkeeping, financial statements and tax reporting may require different classifications and professional guidance. Agents should reconcile their internal profitability tracking with their bookkeeping system and qualified accounting or tax professionals when appropriate.
Compliance Note
This article is provided for general educational and informational purposes only. It is not financial, accounting, tax, legal, investment or brokerage advice and should not be relied upon as a substitute for professional guidance. Commission structures, brokerage agreements, referral arrangements, allowable deductions, tax obligations, employment classifications, advertising costs, business-expense treatment and real estate regulations vary by jurisdiction, brokerage, business entity and individual circumstances. Examples and calculations in this article are hypothetical and are intended only to demonstrate general financial concepts; they do not represent guaranteed income, profit, tax savings or business results. Real estate professionals should verify their commission statements and brokerage agreements and consult their broker, accountant, CPA, tax adviser, attorney or other appropriately qualified professional before making financial, tax, legal or business decisions. Any calculator, spreadsheet or net-sheet template should be treated as an estimation and planning tool rather than an official accounting, settlement or tax document.
Stay ahead with exclusive updates
Join our community. Get curated industry trends, actionable guides, and fresh resources delivered straight to your inbox.